Filing a premises liability claim after a slip and fall is a process, not a single event. It unfolds in stages — incident notice, insurance claim, investigation, negotiation, and, if necessary, a lawsuit — each with its own tasks, timelines, and pitfalls. Knowing the full sequence in advance keeps you from missing steps that are easy to overlook when you are hurt and stressed.
This detailed guide walks the full timeline from the day of the fall to resolution, so you always know what phase you are in, what comes next, and what the other side is doing at each stage.
Phase 1: Incident Notice (Day 1)
Everything starts with notice. Report the fall to the property owner, manager, or on-duty employee immediately — before you leave the premises if you safely can. Ask that an incident report be created and get a copy or at least the report number. This contemporaneous record is the foundation every later phase stands on: it fixes the date, location, and conditions in writing while memories are fresh.
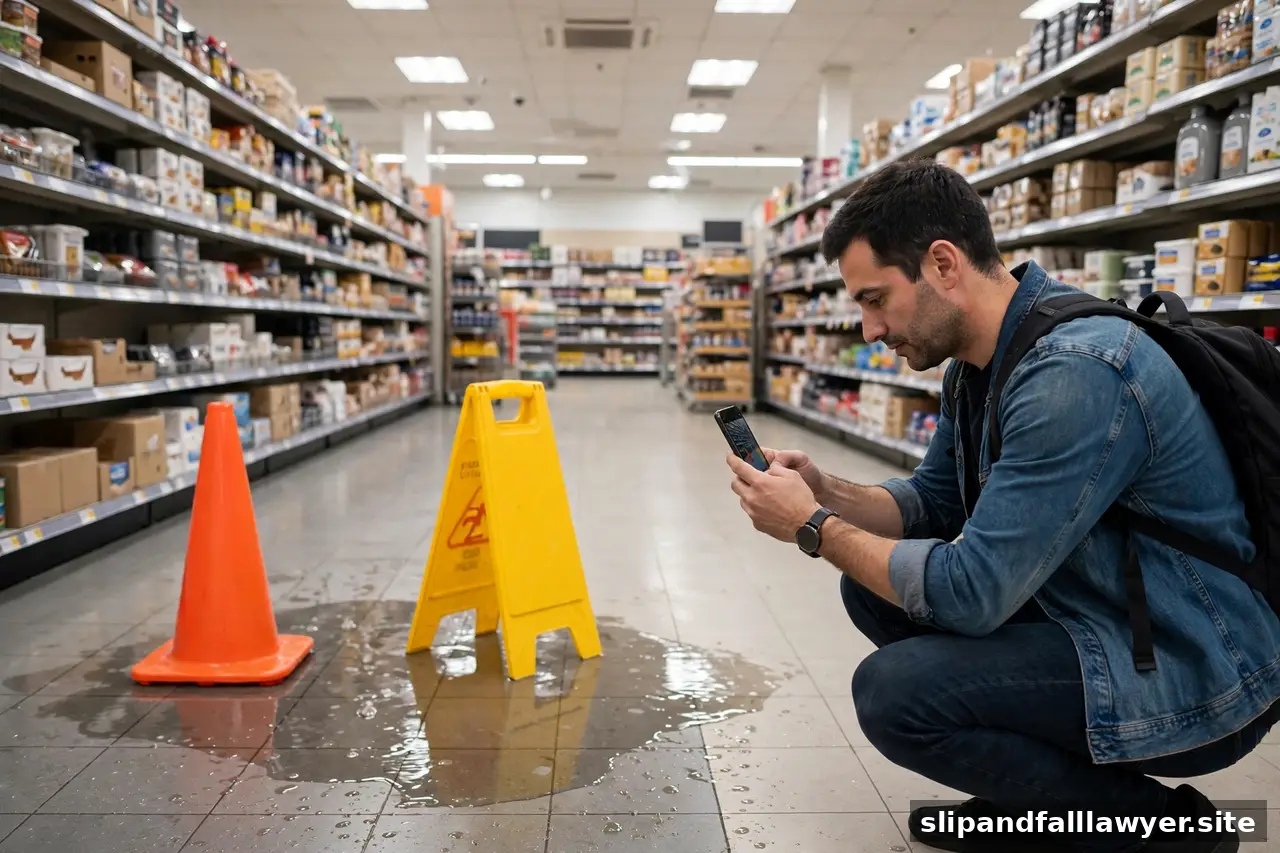
While still at the scene, document aggressively. Photograph the hazard from multiple angles, the surrounding area, lighting conditions, and any warning signs (or their absence). Photograph your visible injuries. Collect names and phone numbers of witnesses — employees and bystanders alike. Our evidence checklist after a fall walks through each item to capture in these first critical hours. If you need emergency care, get it; health comes first, and medical records created on day one are the strongest evidence of causation you will ever have.
Phase 2: Medical Treatment and Documentation (Days 1–90+)
Follow through on all medical care: emergency treatment, primary care follow-up, referrals to specialists, physical therapy, imaging — whatever your providers recommend. This phase runs in parallel with everything else, and it is the engine of your claim’s value. Every visit creates a record; every gap creates a question the other side will ask. Keep a simple file of bills, discharge instructions, and prescriptions as you go.
Start a daily journal now. Note pain levels, sleep disruption, missed work, activities you cannot do, and how the injury affects ordinary life. Two sentences a day is enough. Months later, when an adjuster asks how the injury affected you, this journal turns vague memory into specific, dated evidence. Also track every out-of-pocket cost — mileage to appointments, over-the-counter supplies, help you had to hire at home. Small costs add up, and undocumented costs vanish. Photograph your injuries as they heal, too: a dated series of photos showing bruising, swelling, or surgical scars tells a story that words alone cannot, and adjusters respond to visual evidence.
Phase 3: Opening the Insurance Claim (Weeks 1–4)
Once you know the property owner’s insurer — ask the owner or manager directly, in writing — open a claim and get a claim number. Provide the basic facts: who you are, when and where the fall happened, and that you were injured. Keep this initial report brief and factual; detailed narratives can wait until you understand the full extent of your injuries.
Expect an adjuster to be assigned within days. From this point forward, be polite, be factual, and put things in writing — and keep building your evidence file in parallel. The evidence checklist after a fall shows exactly what to preserve and how to organize it while the details are fresh.
Phase 4: Building the Liability Case (Weeks 2–12)
While treatment continues, the liability picture gets assembled. Key questions: What was the hazard, and how long had it existed? Did the owner know about it — through prior complaints, inspection logs, or employee knowledge? Were there warning signs, adequate lighting, handrails? Were maintenance or cleaning procedures followed?
Evidence for these questions comes from your photos, the incident report, witness statements, and — critically — records you may need to request formally: surveillance footage (request it immediately; many systems overwrite within days), maintenance logs, cleaning schedules, and prior complaint records. If you hire an attorney, this is where they earn their keep, using formal discovery tools you cannot access on your own. Strong liability evidence, documented early, is what moves settlement offers later — because carriers price every claim against the risk of losing the liability argument at trial.
Phase 5: The Demand Letter (When Treatment Stabilizes)
Once your medical picture is clear — treatment complete or your condition stable enough to project future needs — it is time to make a formal demand. The demand letter lays out liability, describes your injuries and treatment, itemizes your losses, and states the amount you will accept to settle. It is the document that converts months of preparation into a negotiating position.
Writing an effective demand is a skill in itself, which is why we have a dedicated walkthrough: How to Write a Demand Letter That Gets Taken Seriously. The key principle: every claim in the letter must trace to a document in your file. A demand built on records commands respect; a demand built on adjectives invites a low counter. If new symptoms surface after the demand goes out, you can supplement it — but a complete first demand sets a stronger anchor, so avoid rushing this step before your medical picture is stable.
Common Detours: What Slows Claims Down
Not every claim moves cleanly through the phases above. The most common detour is a liability dispute: the owner claims the hazard was open and obvious, blames a contractor, or argues you were trespassing. Each defense adds investigation rounds and sometimes requires hiring experts — engineers, safety consultants — to rebut. These disputes do not kill claims, but they stretch timelines by months.
Medical complications cause the second detour. If your treatment reveals a pre-existing condition in the same body part, the carrier will argue apportionment — that only part of your harm came from the fall. Your providers’ notes distinguishing the new injury from the old condition become critical evidence. Be upfront with your doctors about your full history; surprises in old records hurt far more than honest disclosures.
The third detour is lienholder gridlock. Health insurers, Medicare or Medicaid, and medical providers with liens must all be dealt with before disbursement, and bureaucratic lienholders move slowly. Start identifying lienholders during Phase 5, not Phase 8 — early notice prevents the frustrating scenario of an agreed settlement sitting in escrow for months while paperwork crawls.
Phase 6: Negotiation (Weeks to Months)
The adjuster will respond to your demand — usually with a counter far below it. This is normal. Negotiation proceeds in rounds: their number, your number, converging toward agreement or toward an impasse. Each round should be in writing, each concession tied to a reason. Never negotiate against yourself by lowering your demand without receiving movement in return.
Several rounds are typical, and the process can take weeks or months. Stay patient and keep treating if care is ongoing. If the gap between positions will not close, mediation — a structured negotiation with a neutral facilitator — resolves many cases that direct talks cannot. Throughout, keep one eye on the calendar: negotiation does not pause the statute of limitations, and filing a lawsuit to protect the deadline is a procedural step, not a declaration of war.
Phase 7: Filing a Lawsuit (If Needed)
If negotiation stalls or the deadline approaches, filing suit preserves your rights and changes the dynamic. After filing comes discovery — both sides exchange documents, answer written questions, and give depositions — then pretrial motions, and potentially mediation or trial. Discovery is often where cases are truly won or lost: internal maintenance records, employee testimony, and surveillance footage surface here, and each side’s case gets stress-tested under oath. The majority of filed cases still settle before trial, often after discovery clarifies the strengths and weaknesses each side was guessing at.
Litigation takes time, commonly a year or more, and it demands more from you: depositions, medical examinations by defense doctors, and detailed document production. An experienced premises-liability attorney is near-essential from this phase onward and can advise whether regular civil court is the right forum for your case’s size and complexity.
Phase 8: Resolution and Disbursement
Settlement or verdict is not the finish line — disbursement is. From the gross amount, medical liens must be negotiated and paid, attorney fees and case costs deducted, and any remaining balances resolved. Only then do you receive your share, as a single payment or as scheduled payments over time. Review the settlement statement line by line before signing the release; errors here are rare but costly. Read the release language itself with equal care: it typically waives all claims arising from the incident, known and unknown, so make sure you understand exactly what rights you are giving up and that the released parties are correctly identified. Once signed, a release is extraordinarily difficult to undo — there is no cooling-off period.
Disclaimer: This article is general information, not legal advice. Laws vary by state — consult a licensed attorney about your situation.
The claim process rewards the organized and the patient. Report promptly, document relentlessly, treat consistently, and always understand which phase you are in at all times. Each phase builds on the last — and the careful work you do in phase one echoes all the way to phase eight. Most importantly, remember that the process is a means to an end: fair compensation for real harm. Keep your records straight, your expectations grounded, and your deadlines calendared, and you will navigate the system from a position of real strength rather than scrambling to catch up.