When people think about the cost of a slip-and-fall injury, they usually picture the emergency room bill. That bill matters, but it is often the smallest part of the story. The real financial weight of a serious fall unfolds over months and years: follow-up surgeries, months of physical therapy, time away from work that stretches into lost earning capacity, modifications to a home that no longer fits the person living in it. These long-term costs are the ones most people miss — and the ones most likely to be undervalued in a quick settlement.
This article walks through the categories of long-term cost that fall injuries commonly produce. It is qualitative by design: every injury and every life is different, and no article can put a number on yours. The goal is to make sure that when you — or anyone evaluating your claim — tally what the fall truly cost, nothing important is left off the page. Our guide to medical documentation is the companion piece: every cost below needs to be documented to be recoverable.
Why Long-Term Costs Get Missed
There are three reasons future costs slip through the cracks. First, timing: the full extent of an injury often is not clear for months. A knee that “just needs therapy” becomes a knee that needs surgery a year later. A back strain becomes a chronic disc problem. Early in a claim, nobody — including your doctors — can say with certainty what the next two years hold, which makes it tempting to settle based on what is known today.
Second, invisibility: many long-term costs are not medical bills. They are the hours a spouse spends helping you dress, the promotion you missed while on restricted duty, the staircase you can no longer climb. These losses are real, but they do not arrive as invoices, so they get overlooked in negotiations focused on paperwork.
Third, pressure to settle: insurers often make early offers before the long-term picture is clear, and the offer looks generous against the bills received so far. Accepting it closes the door on everything discovered later. Understanding the full menu of potential future costs is your best defense against settling too soon for too little — a dynamic our breakdown of settlement range factors explores in detail.
Future Medical Care
The most obvious long-term cost is also the easiest to underestimate. Beyond the initial treatment, serious fall injuries commonly require follow-up surgeries (hardware removal, revision procedures), ongoing specialist visits, diagnostic imaging to monitor healing, prescription medications taken for extended periods, and pain management interventions such as injections. Each of these is individually foreseeable once the injury is understood — which is why attorneys in significant cases often work with treating physicians or life-care planners to project future medical needs in writing.
The key question to ask your doctor, once the acute phase passes, is forward-looking: what is reasonably likely to be needed from here? A written treatment plan that extends into the future transforms speculation into documentation. Without it, future care is an argument; with it, it is a line item.
Rehabilitation and Therapy
Recovery from fractures, surgeries, and serious soft tissue injuries is measured in months of rehabilitation, not days. Physical therapy to rebuild strength and mobility, occupational therapy to relearn daily tasks, and in the case of brain injuries, cognitive or speech therapy — these programs are essential, time-consuming, and ongoing. A single course of therapy may not be enough; setbacks and plateaus often require additional rounds.
There is also the therapy nobody prescribes but many people need: treatment for the psychological aftermath. Falls — especially those causing lasting disability — commonly produce anxiety, depression, sleep disruption, and in some cases post-traumatic stress around the circumstances of the fall. Mental health treatment is a legitimate, compensable component of recovery, and it belongs in both your treatment plan and your claim. Do not let stigma keep it out of either.
Lost Earning Capacity
Missed paychecks in the weeks after a fall are straightforward to calculate. Lost earning capacity — the difference between what you would have earned over your working life and what you can earn now — is subtler and often far larger. A warehouse worker who can no longer lift, a nurse who can no longer stand for twelve-hour shifts, a tradesperson whose grip never fully returns: the injury does not just cost them weeks of wages, it can cost them their occupation.
Even when a career change is possible, it often comes at a lower wage, with retraining costs and a delayed trajectory. Documenting this category means documenting the before and after: your work history, your earnings, the physical demands of your job, your doctor’s work restrictions, and any vocational assessment of what work remains available to you. Employers’ letters confirming missed time, lost promotions, or forced role changes strengthen the record considerably.
Home Modifications and Daily Living
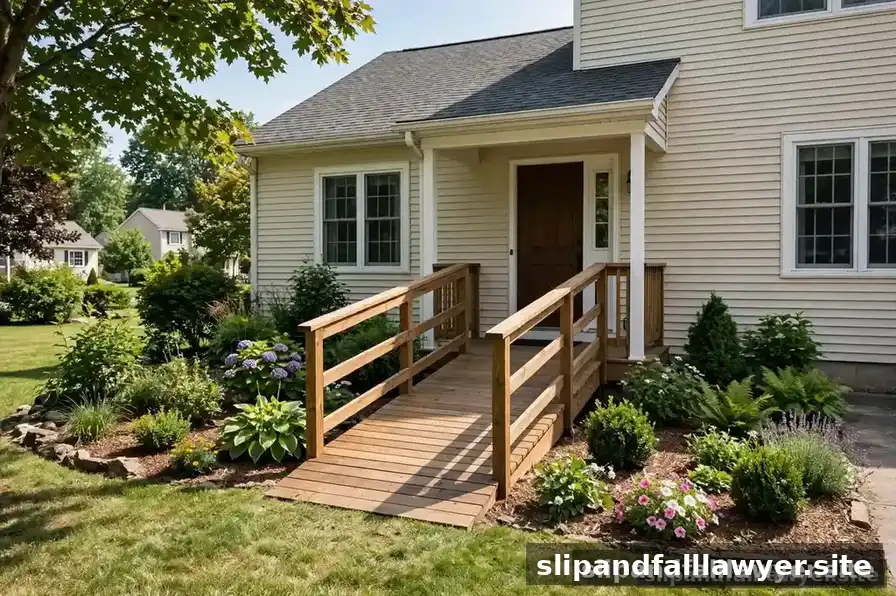
Serious injuries can make an ordinary home an obstacle course. Stairs become barriers; bathtubs become hazards; doorways too narrow for mobility aids become daily frustrations. Common modifications include ramps, stairlifts, walk-in showers with grab bars, widened doorways, and main-floor bedroom conversions. For severe injuries, the modifications can extend to vehicle adaptations or even relocation to accessible housing.
Alongside the physical changes are the human ones: the hours of help needed with cooking, cleaning, dressing, transportation to appointments, and childcare during recovery. Family members provide most of this care, usually unpaid — which does not make it free. The market value of that care, and the burden on the people providing it, are recognized components of what an injury costs, even when no money changes hands.
The Ripple Effects: Family, Work, and Daily Life
Some of the heaviest long-term costs never appear on a bill because they are paid in other people’s time and in opportunities quietly lost. A spouse who cuts back work hours to provide care. Children who take on household responsibilities no child should have to manage. Hobbies, exercise routines, and social lives that shrink around the injury’s limitations — the loss of enjoyment of life is a recognized category of harm precisely because these invisible subtractions are real.
Career ripple effects deserve particular attention. An injury that forces a job change often resets seniority, benefits accrual, and retirement contributions, compounding over decades. Even workers who return to the same role may find themselves passed over for physically demanding assignments or promotions, with the earnings gap widening year after year. When documenting your claim, think beyond this year’s W-2: performance reviews, promotion trajectories, and pension or benefits statements all help show what the injury disrupted, not just what it immediately cost.
Children and Older Adults: Special Long-Term Considerations
Long-term costs look different at different ages. For children, a serious fall injury can affect growth plates, require surgeries timed to physical development, and create needs that evolve as the child grows — a settlement reached at age eight must account for the teenager the child will become. For older adults, the concern runs the other direction: a fall injury can accelerate loss of independence, turning a self-sufficient person into someone who needs assisted living years earlier than expected. The cost difference between independent living and full-time care is enormous, and when a fall triggers that transition, the fall bears responsibility for the gap.
Both situations share a common trap: valuing the claim based on the patient’s condition today rather than the trajectory the injury set in motion. Pediatric and geriatric injuries demand the longest view of all, because the timeline of consequences is measured in decades, not months.
Documenting Future Costs Before They Arrive
Future costs feel speculative until they are documented, and documentation is a skill. Ask treating physicians for written opinions about likely future treatment, not just current diagnoses. Keep a log of every way the injury limits daily life — the stairs avoided, the activities abandoned, the help required — because these notes become the raw material for describing long-term impact. Save every receipt related to the injury, including the unglamorous ones: parking at the hospital, the shower chair, the rideshare to therapy when you could not drive.
For significant injuries, professionals exist to formalize all of this: life-care planners who project future medical needs, economists who model lost earning capacity, vocational experts who assess work limitations. You do not need these experts for every claim, but knowing they exist — and that insurers take their reports seriously — helps you understand what a complete accounting looks like.
Lump Sum or Structured Payments
When long-term costs are substantial, how compensation is paid matters almost as much as how much. A lump sum delivers everything at once: maximum flexibility, but also maximum responsibility — and the risk that the money runs out before the needs do. A structured settlement spreads payments over years, matching the timeline of ongoing costs and providing steady, predictable support, at the cost of flexibility.
Neither option is right for everyone. The choice depends on the size and duration of your future needs, your financial discipline and situation, tax considerations, and eligibility for needs-based programs. A young person facing decades of future care has very different needs from someone whose costs are concentrated in the next two years, and the decision is difficult to reverse once made. Our comparison of structured settlements versus lump sums walks through the trade-offs in detail. The key insight for this article’s purposes: if your claim involves years of future costs, the payment structure deserves as much thought as the total figure.
The long-term costs of a fall injury are the costs nobody warns you about in the emergency room. Map them early, document them relentlessly, and do not let anyone — including your own impatience — rush you into valuing your claim before the full picture is visible. What you miss now, you pay for later.
Disclaimer: This article is general information, not legal advice. Laws vary by state — consult a licensed attorney about your situation.